Financial Virtual Assistant: What They Do and Why Businesses Hire Them
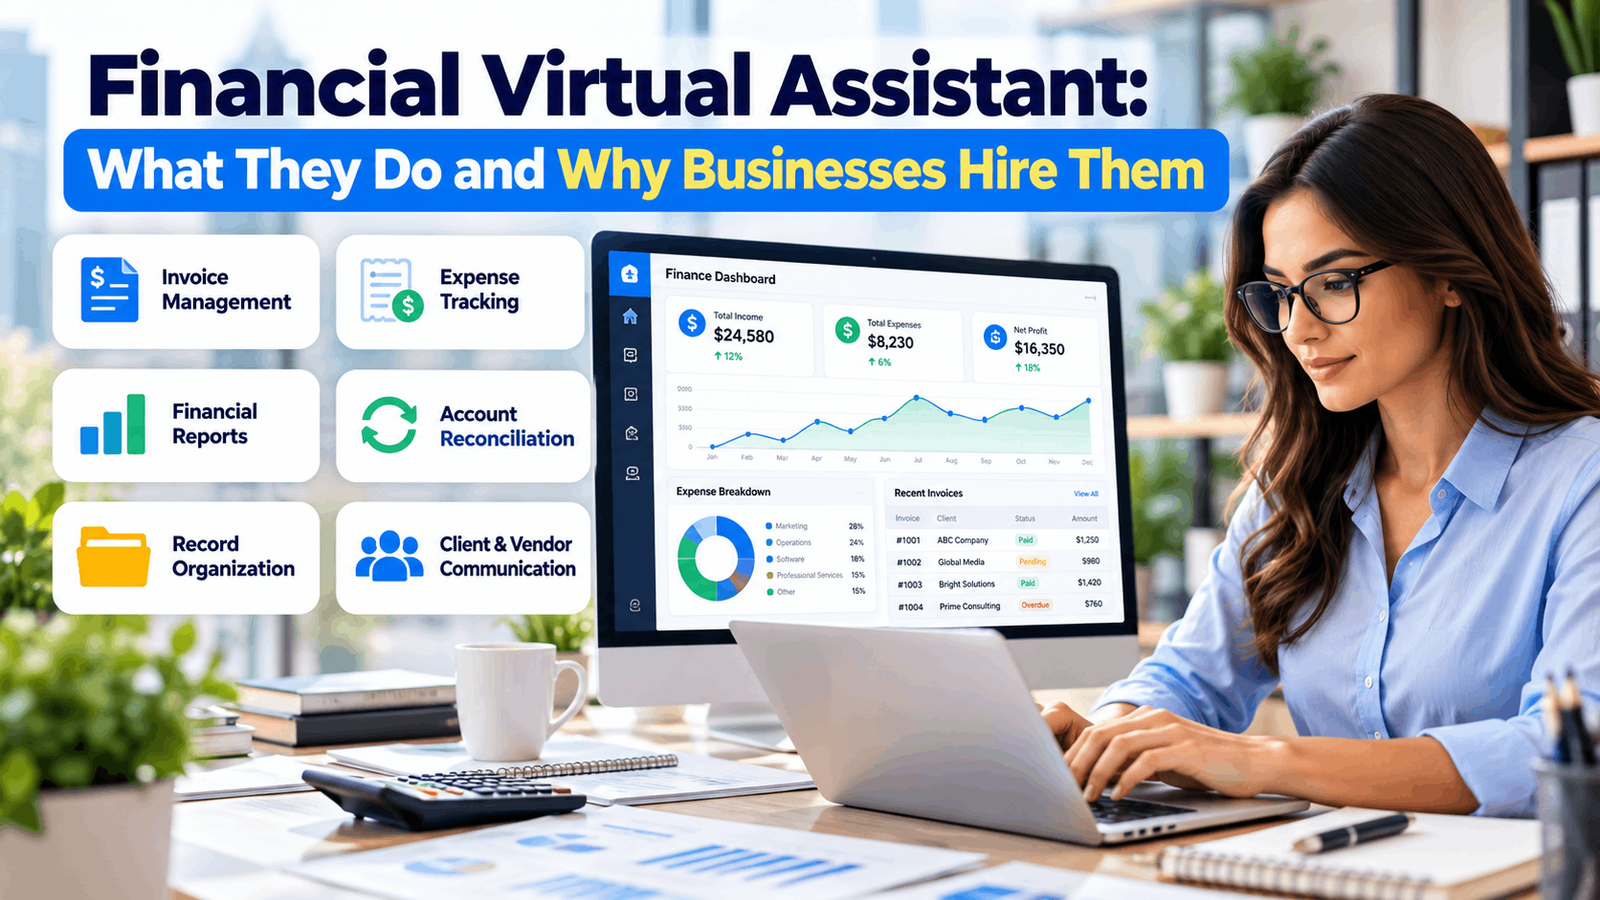
A financial virtual assistant helps businesses manage recurring financial and administrative tasks without requiring owners, managers, or senior employees to handle every detail themselves. Depending on the role, this support may include invoice administration, expense tracking, financial record organization, reconciliation support, report preparation, client communication, and related routine work.
For growing U.S. businesses, financial administration often becomes more demanding as transaction volume, customers, vendors, invoices, and reporting requirements increase. The work matters, but not every task requires the direct attention of an owner, controller, or senior financial professional.
That is where a well-defined remote financial support role can become valuable.
The goal is not to replace accountants, CPAs, tax professionals, or financial decision-makers. Instead, businesses can delegate appropriate process-driven work while keeping approvals, professional accounting responsibilities, and financial authority with qualified internal or external professionals.
What Is a Financial Virtual Assistant?
A financial virtual assistant is a remote professional who supports selected financial and administrative processes for a business.
The exact role varies considerably from one company to another.
A small business may need help organizing invoices, tracking expenses, and preparing routine reports. Another company may need support maintaining financial records, communicating with clients, coordinating appointments, or preparing information for its accounting team.
The important distinction is that a financial virtual assistant generally supports financial operations and administration rather than automatically assuming the responsibilities of a CPA, accountant, controller, financial adviser, or tax professional.
UpSource Media currently lists Financial Services among its remote assistance areas. Its published services include support with client communication, report preparation, data analysis, and appointment management. Its broader content also identifies bookkeeping and accounting support functions such as invoice management, expense tracking, account reconciliation support, financial record organization, and report preparation. UpSource Media
What Does a Financial Virtual Assistant Do?
The responsibilities should always reflect the business’s processes, systems, security requirements, and the professional’s qualifications.
However, several recurring financial tasks may be suitable for remote support.
1. Invoice Administration
Invoices are essential to business operations, but managing them can involve repetitive administrative work.
A financial virtual assistant may help organize invoice information, prepare approved invoice data, update records, monitor invoice status, and maintain supporting documentation according to established company procedures.
The business should still define who can approve invoices, authorize changes, issue credits, or make other financial decisions.
Separating preparation from approval can create clearer internal controls.
2. Expense Tracking and Organization
Business expenses generate records that need consistent organization.
Receipts, vendor information, transaction details, and supporting documents can quickly accumulate when nobody clearly owns the process.
A remote financial professional may help organize expense information, update approved systems, categorize documents according to established procedures, and flag incomplete records for review.
This work also supports better recordkeeping.
The IRS recordkeeping guidance explains that businesses need records that clearly show income and expenses. Good records also support financial statement preparation, expense tracking, tax-return preparation, and items reported on tax returns. IRS
However, decisions about tax treatment, deductions, accounting methods, and tax filings should remain with appropriately qualified professionals.
3. Financial Record Organization
Financial information often comes from several sources.
Businesses may receive invoices, receipts, statements, customer records, vendor documents, spreadsheets, and reports throughout the month.
Without a consistent process, finding the correct information later can become unnecessarily difficult.
A financial virtual assistant can help maintain an organized record-management workflow.
For example, the role might involve following established file-naming standards, organizing documents in approved folders, updating records, checking whether required information is present, and preparing documentation for internal financial staff.
Organization may sound simple, but consistency becomes increasingly important as a business grows.
4. Account Reconciliation Support
Reconciliation helps businesses compare financial records and identify differences that need attention.
Depending on qualifications and company procedures, remote support may assist with the administrative side of reconciliation.
For example, a financial virtual assistant may gather relevant records, organize supporting documentation, update approved information, identify apparent discrepancies, and prepare items for review.
UpSource Media has specifically identified account reconciliation support among the bookkeeping and accounting functions that remote professionals may assist with. UpSource Media
However, businesses should clearly determine who reviews discrepancies, makes adjustments, approves entries, and accepts final financial reports.
5. Report Preparation
Managers need useful information to understand what is happening inside a business.
Unfortunately, preparing routine reports can consume significant employee time.
A financial virtual assistant may help collect approved information, organize data, update recurring reports, prepare summaries, and ensure that reports follow established formats.
The role does not need to make strategic decisions based on the report.
Instead, the assistant can help prepare organized information so owners, managers, accountants, or finance professionals can review it and make appropriate decisions.
Report preparation is one of the financial support functions currently listed by UpSource Media. UpSource Media
6. Accounts Receivable Administration
Making a sale does not end the financial process.
Businesses also need to manage invoices, maintain customer records, monitor outstanding balances, and follow established procedures for payment communication.
A financial virtual assistant may support routine accounts receivable administration when the company provides clear workflows.
Depending on the role, this could involve maintaining invoice records, organizing customer account information, updating payment statuses, preparing routine reports, or completing approved follow-up activities.
For businesses that need deeper information on this area, UpSource Media’s accounts receivable outsourcing guide explains how remote professionals can support selected AR processes while businesses retain appropriate financial controls. UpSource Media
7. Client and Vendor Communication
Financial administration frequently requires communication.
A customer may have a question about an invoice. A vendor document might be incomplete. An internal employee may need supporting information before approving an item.
Not every communication requires a senior finance employee.
With approved procedures and communication standards, a remote professional can handle appropriate routine correspondence and direct exceptions to the correct person.
This is particularly relevant because UpSource Media’s financial services offering specifically identifies client communication as one of the functions its virtual assistants can support. UpSource Media
8. Appointment and Schedule Management
Financial professionals often have meetings with customers, vendors, internal teams, accountants, advisers, or other stakeholders.
Scheduling those meetings creates additional administrative work.
A financial virtual assistant may coordinate calendars, confirm appointments, organize meeting information, and help keep schedules current.
Although this responsibility is less directly connected to bookkeeping, it can still reduce administrative pressure on financial professionals.
UpSource Media includes appointment management within its published Financial Services support. UpSource Media
What Should a Financial Virtual Assistant Not Do?
Businesses should avoid treating the phrase “financial virtual assistant” as permission to delegate every financial responsibility.
Some tasks require specific qualifications, professional judgment, internal authority, or regulatory expertise.
Depending on the business and jurisdiction, responsibilities that may need to remain with appropriately qualified professionals include tax advice, tax-return preparation where professional credentials are required, audits, legal advice, investment advice, accounting-policy decisions, complex financial analysis, final financial approvals, and other regulated or high-authority activities.
The boundaries should be established before the role begins.
A useful principle is to separate support and preparation from professional judgment and financial authority.
For example, a remote assistant may organize expense records. A qualified tax professional can determine how those expenses should be treated for tax purposes.
Likewise, an assistant might prepare information for a financial report, while authorized management reviews the information and makes business decisions.
Financial Virtual Assistant vs. Bookkeeper
These roles can overlap, but they are not automatically the same.
A bookkeeper generally focuses more specifically on maintaining financial records and recording business transactions according to an established bookkeeping system.
A financial virtual assistant can have a broader administrative role.
For example, the position might combine invoice administration, document organization, client communication, appointment management, report preparation, and selected bookkeeping-support tasks.
Therefore, businesses should focus less on the job title and more on the actual responsibilities.
Before hiring, define exactly what the person will do, which systems they will use, what qualifications they need, and which tasks require approval.
Financial Virtual Assistant vs. Accountant or CPA
This distinction is even more important.
A financial virtual assistant should not automatically be treated as a replacement for an accountant or CPA.
Accountants may handle responsibilities requiring deeper accounting knowledge and professional judgment. CPAs may also perform services that require specific professional credentials or licensing.
A remote assistant, meanwhile, can support the recurring administrative processes around the financial function.
These roles can complement each other.
For example, a virtual assistant can help maintain organized documentation throughout the month. When the accountant needs information, the records may already be prepared according to the company’s established process.
The result is a clearer division of responsibilities rather than an attempt to make one person responsible for everything.
Why Do Businesses Hire Financial Virtual Assistants?
One common reason is workload.
As companies grow, financial administration tends to grow with them.
More customers can mean more invoices. Additional vendors create more documents. Higher transaction volume produces more records, while expanding teams can create additional reporting and administrative requirements.
Initially, business owners or existing employees may absorb the work.
However, that approach can become difficult to sustain.
A business owner may spend evenings organizing financial documents. An operations manager might repeatedly update reports. Meanwhile, an experienced accountant could spend time chasing routine paperwork instead of focusing on work that requires accounting expertise.
A financial virtual assistant gives businesses another way to distribute those responsibilities.
A Financial Virtual Assistant Can Create Clearer Role Separation
Delegation is not simply about removing work from someone’s schedule.
It can also help businesses place responsibilities with the appropriate people.
Consider a company where the owner handles customer relationships, approves expenses, reviews invoices, organizes receipts, updates spreadsheets, and prepares information for the accountant.
Some of those responsibilities genuinely require the owner’s authority.
Others do not.
The owner may still approve payments and make financial decisions. However, a trained remote professional could potentially handle defined administrative preparation.
That separation allows the owner to maintain control without personally completing every step.
When Does a Business Need a Financial Virtual Assistant?
There is no universal company size or revenue threshold.
Instead, look at how work currently moves through the business.
A remote financial support role may be worth evaluating when routine financial administration regularly falls behind, senior employees spend too much time organizing records, invoices lack consistent follow-up, reports take too long to prepare, documentation becomes difficult to find, or recurring financial tasks do not have a clear owner.
The important question is not simply, “Are we busy?”
Ask instead:
Which recurring financial tasks consume time without requiring the specific expertise of the person currently doing them?
The answer can reveal which responsibilities are strong candidates for delegation.
What Makes a Good Financial Virtual Assistant Service?
A strong financial virtual assistant service should begin with role definition rather than a generic list of tasks.
The provider and business should understand what work needs to be completed, which skills the role requires, what systems are involved, how sensitive information will be handled, and who maintains approval authority.
Businesses should also evaluate communication skills, relevant experience, process discipline, availability, security awareness, and the ability to follow documented procedures.
In addition, determine how the professional will integrate with existing employees.
Remote financial support should not operate as an isolated function. The person may need clear communication channels with operations, management, accounting, customer service, or external financial professionals.
Establish Internal Controls Before Delegating Financial Work
Financial tasks deserve additional attention because they can involve sensitive information and access to important business systems.
Businesses should establish controls before granting access.
Start by defining exactly what the remote professional can view, edit, prepare, or approve.
Where possible, avoid giving unrestricted administrator access simply because it is convenient.
Approval authority should also remain clear.
For example, an assistant may prepare information related to an invoice while an authorized manager approves it. Similarly, the assistant might organize payment information without having authority to initiate or approve payments.
Clear controls protect the business while making the role easier to manage.
Protect Financial Accounts and Business Data
Security should form part of the onboarding process.
Use individual accounts where systems support them. Limit permissions to what each role actually needs, and remove access promptly when responsibilities change.
Multifactor authentication should also be considered for business systems containing sensitive information. The CISA guidance on multifactor authentication recommends requiring MFA wherever possible, particularly for administrative accounts and employees handling sensitive data. CISA
Businesses can also review CISA’s cybersecurity resources for small and medium-sized businesses for guidance covering passwords, MFA, backups, encryption, software updates, and other security practices. CISA
Document Financial Processes Before Hiring
A new remote professional cannot follow a process that nobody has defined.
Before onboarding, document recurring responsibilities.
For each task, explain what starts the process, where the required information comes from, which steps need completion, what the expected result looks like, who approves the work, and which situations require escalation.
For example, an invoice workflow might explain how supporting information is received, where records are stored, what information must be checked, who reviews the invoice, and what happens when information is missing.
Documentation makes expectations clearer for everyone involved.
It also helps the company maintain consistency when responsibilities change.
How to Measure Financial Virtual Assistant Performance
Performance metrics should match the role.
A financial virtual assistant responsible for administrative support should not be evaluated as though they were the company’s CFO.
Instead, measure the responsibilities assigned to them.
Useful measures may include task completion, record accuracy, documentation quality, timely report preparation, adherence to procedures, appropriate escalation, communication quality, and unresolved workload.
Accuracy deserves particular attention.
Completing a large number of tasks quickly provides little value if the information requires repeated correction.
Therefore, businesses should balance productivity with accuracy, consistency, and process compliance.
Common Mistakes When Hiring Remote Financial Support
One mistake is creating a vague role.
“Help us with finance” does not clearly explain what the person should do.
Instead, define responsibilities such as invoice administration, expense organization, report preparation, record management, or account reconciliation support.
Another mistake is granting excessive access.
A remote professional should receive the permissions necessary for the role, not automatic access to every financial system.
Businesses can also run into problems when they delegate work without documenting procedures.
Even an experienced professional needs to understand the company’s specific systems, approval rules, communication standards, and reporting requirements.
Finally, avoid expecting administrative support to replace specialized financial expertise.
Financial virtual assistance works best when the role complements accountants, bookkeepers, management, and other qualified professionals.
How UpSource Media Supports Financial Operations
UpSource Media provides virtual employment and remote business support for U.S. companies seeking additional operational capacity.
Its current Financial Services offering includes virtual-assistant support for client communication, report preparation, data analysis, and appointment management. In its broader published content, the company also identifies bookkeeping and accounting support activities such as invoice management, expense tracking, account reconciliation support, financial record organization, and report preparation. UpSource Media
Businesses considering financial support alongside other recurring operations can also explore UpSource Media’s services or its guide to back office support services. UpSource Media
The right approach starts by identifying which tasks need support and separating routine execution from responsibilities requiring financial authority or specialized professional expertise.
Frequently Asked Questions
What Is a Financial Virtual Assistant?
A financial virtual assistant is a remote professional who supports selected financial and administrative processes. Responsibilities may include invoice administration, expense organization, record management, reconciliation support, report preparation, client communication, and other recurring tasks, depending on the role and qualifications.
What Tasks Can a Financial Virtual Assistant Handle?
The role may support invoices, expenses, financial documentation, recurring reports, account records, customer communication, appointment scheduling, and selected bookkeeping processes. Businesses should define responsibilities according to their own workflows and the professional’s qualifications.
Is a Financial Virtual Assistant the Same as an Accountant?
No. The roles can overlap in some administrative areas, but a financial virtual assistant should not automatically be treated as an accountant, CPA, tax professional, or financial adviser. Businesses should use appropriately qualified professionals for work requiring specialized expertise, credentials, or professional judgment.
Can a Financial Virtual Assistant Help With Bookkeeping?
A financial virtual assistant may support selected bookkeeping-related tasks when they have appropriate experience and the company provides clear procedures. However, businesses should define the role carefully and retain suitable professional oversight where required.
Can a Financial Virtual Assistant Prepare Taxes?
Businesses should not assume that a virtual assistant is qualified to provide tax advice or prepare tax filings. Tax responsibilities should be handled by appropriately qualified professionals based on the company’s circumstances and applicable requirements.
How Do I Know if My Business Needs Remote Financial Support?
Review where your team spends time. If owners, managers, accountants, or other senior employees regularly handle repeatable financial administration that does not require their specific expertise, a remote support role may be worth evaluating.
How Should I Choose a Financial Virtual Assistant Service?
Start by defining the work. Then evaluate candidates or providers based on relevant experience, communication, accuracy, process discipline, security awareness, system familiarity, availability, and their ability to work within your existing approval structure.
Give Routine Financial Work a Clear Owner
A financial virtual assistant can help a business organize recurring financial administration without transferring every financial responsibility outside the internal team.
The strongest approach begins with clear boundaries.
Identify the repetitive work. Document the process. Decide who retains approval authority. Limit system access appropriately, and determine which responsibilities require accountants, CPAs, tax professionals, or other qualified specialists.
Then build the remote role around the work that can be delegated effectively.
For U.S. businesses looking for additional remote capacity, UpSource Media’s services provide information about its financial and broader virtual-assistance capabilities. Businesses ready to discuss a specific role can also contact UpSource Media about their staffing requirements. UpSource Media